

Temple 8 | Deep Dive | April 2026
Sector: Semiconductor Infrastructure/Metrology & Inspection / Advanced Packaging
Focus: Small and Mid-Cap Structural Bottleneck Plays
Time Horizon: 12 to 24 Months
The GPU shortage of 2024 and 2025 was a training-phase phenomenon. It was loud, visible, and universally understood. Every institutional investor on earth owned NVIDIA. Every retail account had a position in AMD. The compute scarcity narrative dominated every earnings call, every analyst note, and every financial media segment for eighteen consecutive months.
That trade is over.
In April 2026, we have entered what Temple 8 calls the Inference Regime. The structural bottleneck has migrated from parallel compute, meaning GPUs, to serial throughput and physical orchestration, meaning CPUs, substrates, inspection tools, and the precision plumbing that holds the entire semiconductor manufacturing process together. The Temple 8 view is that the alpha has already moved upstream, into the layers of the semiconductor stack that most investors have never heard of.
The companies that control these layers are small, unglamorous and they don’t appear on CNBC. They have no retail following and they are, in several cases, the sole commercial provider of a material, a tool, or a subsystem without which no advanced CPU ships in 2026 or 2027.
We are buying a basket of niche small to mid cap companies which act as a tax collector on every CPU produced.
I. Why The Bottleneck Has Moved
As of April 2026, inference workloads now account for 67% of total AI compute, up from 33% just two years ago. This is the first year in history where "Sprinting" (Inference) has structurally decoupled from "Marathoning" (Training). In training, you hide latency behind massive throughput. In inference, you have nowhere to hide. Every 10ms of latency in a sequential token chain (like DeepSeek R1 or GPT-5) translates to a 15% drop in user retention. CPUs like Intel’s Clearwater Forest (18A) and AMD’s Venice (Zen 6) are the only chips designed to "swallow" the sequential bottleneck that GPUs struggle with during high-concurrency inference.
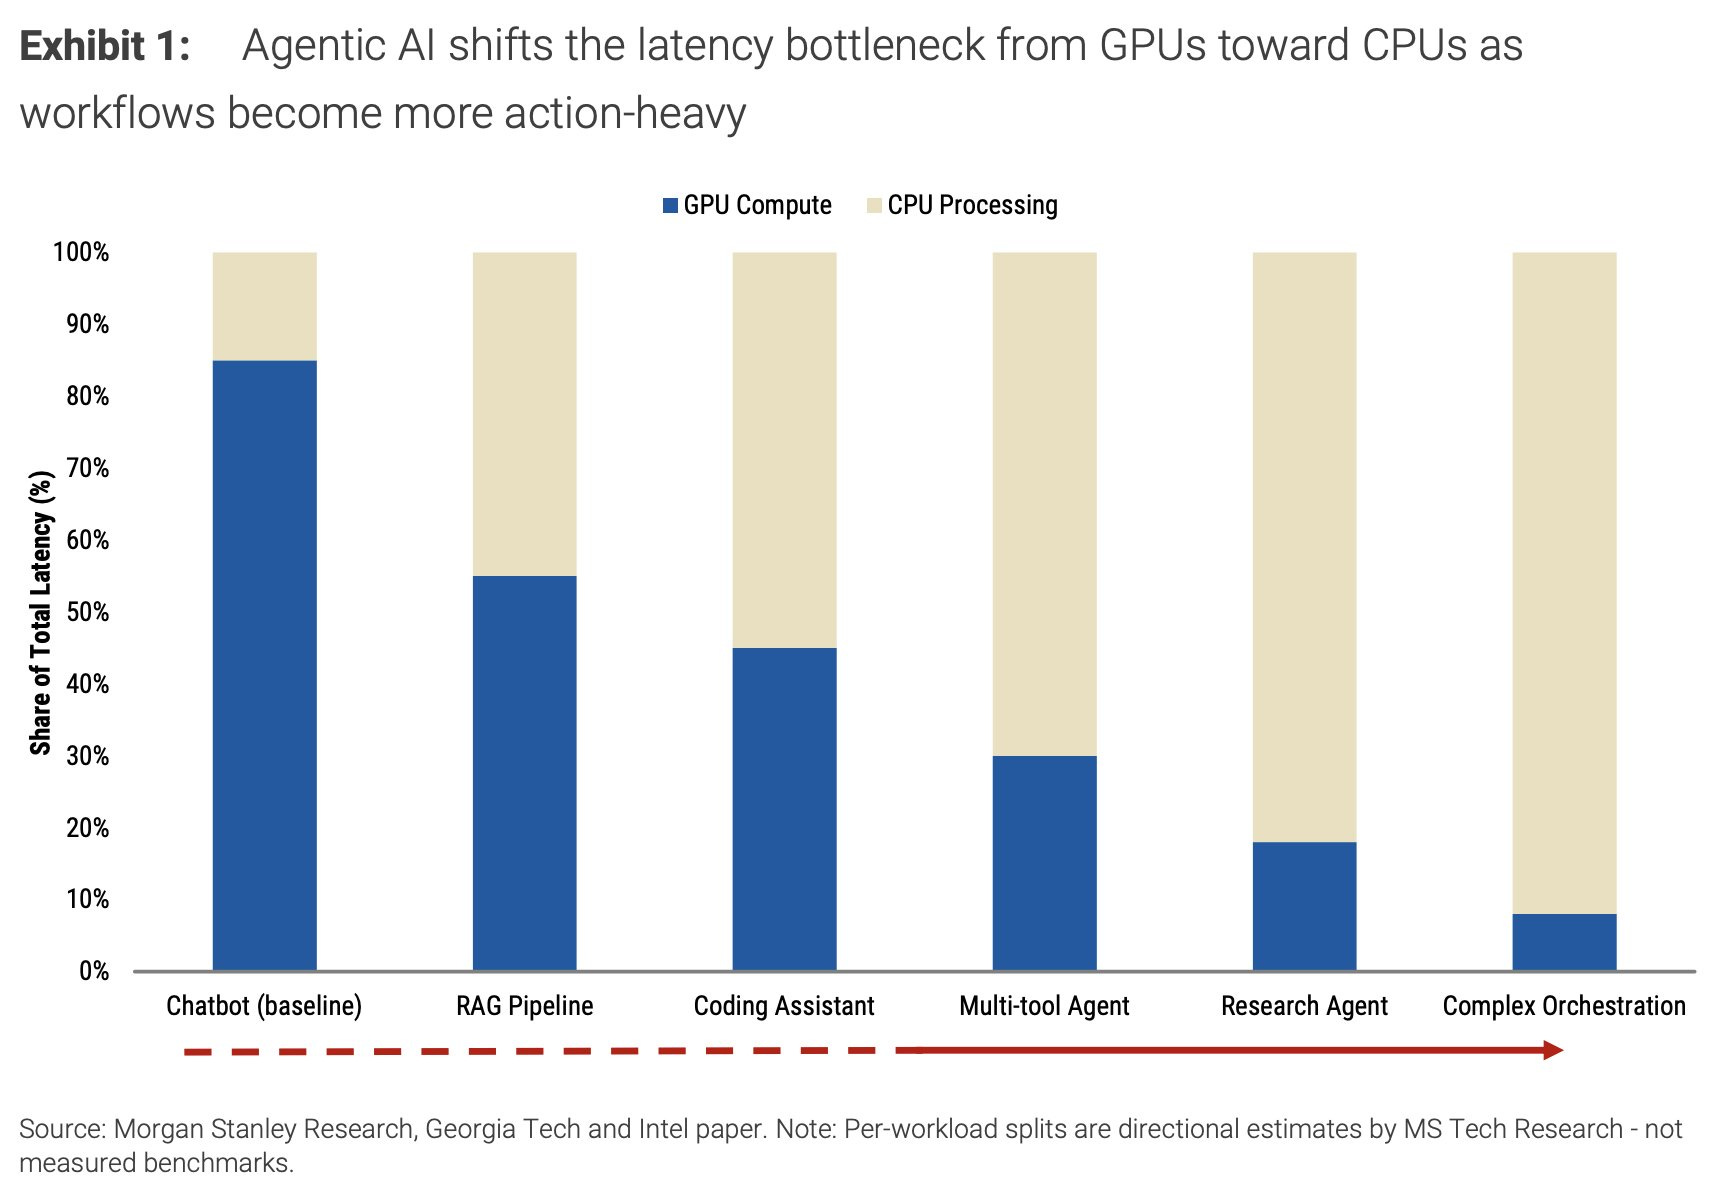
When training a large language model, thousands of GPUs can work simultaneously on independent batches of data. The compute graph is wide. NVIDIA’s architecture is purpose-built for this workload, and nothing competes with it at scale for training.
Inference is different. When a deployed model responds to a user query, the compute graph is sequential. Each token generated depends on the previous one. The bottleneck is not how many operations you can do simultaneously. It is how fast you can complete a single chain of operations. This is the domain of high-throughput CPUs with large cache hierarchies, fast memory access, and low latency photonics interconnects. It is the domain of Intel’s 18A node and AMD’s Turin and Venice architectures. It is the domain that has been under-invested relative to GPU infrastructure for the past three years.
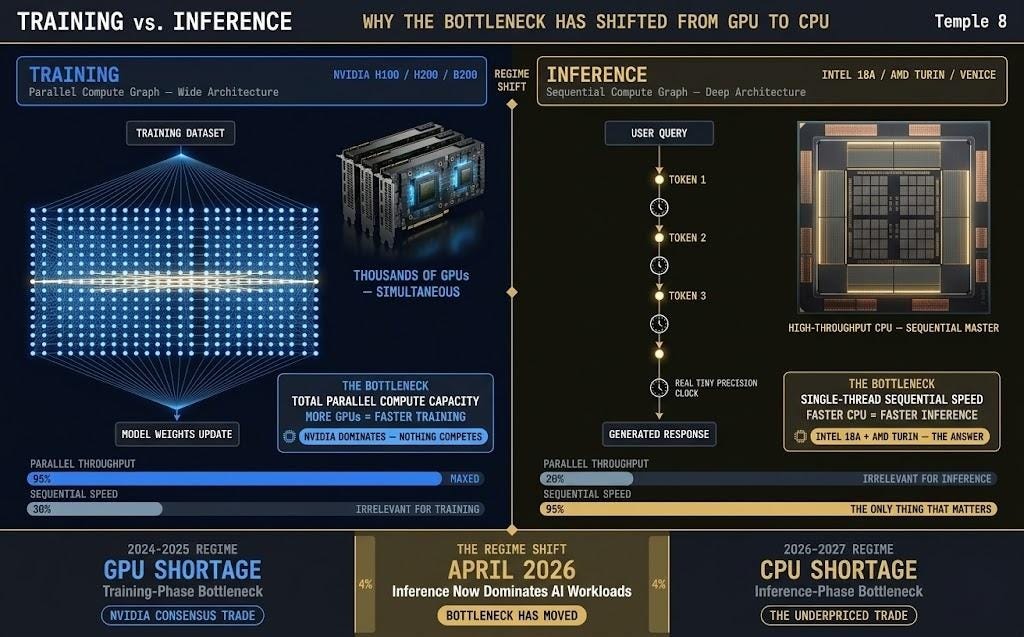
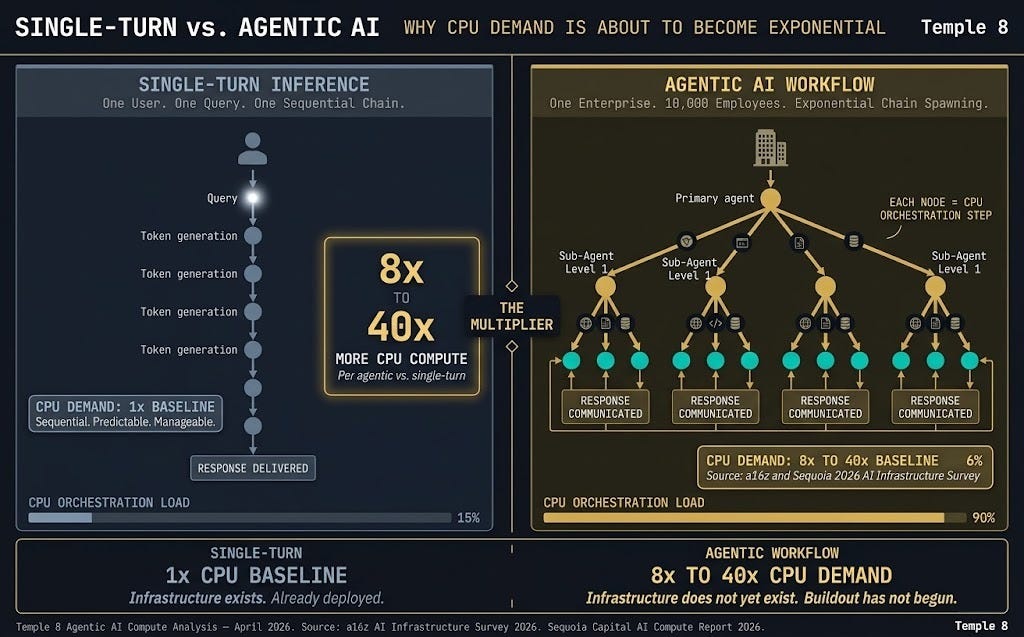
The inference demand curve is non linear. It is about to become exponential, and the reason is agentic AI. Single-user inference, where one person sends one query and receives one response, is already straining inference infrastructure. What is arriving in 2026 and accelerating through 2027 is a categorically different workload: AI agents that run autonomously, spawn sub-agents, call tools, browse the web, write and execute code, and maintain persistent context across sessions that last hours or days rather than seconds. A single agentic workflow from a product like Anthropic's Claude, OpenAI's Operator, or Google's Project Mariner does not generate one sequential token chain. It generates dozens of simultaneous sequential token chains, each one dependent on the results of external tool calls, each one requiring low-latency CPU orchestration between steps. When an enterprise deploys agentic AI across 10,000 employees simultaneously, the CPU inference demand does not multiply by 10,000. It multiplies by 10,000 times the average number of concurrent sub-agent chains each workflow spawns. Industry estimates from Andreessen Horowitz and Sequoia's 2026 AI infrastructure surveys suggest that agentic workloads consume between 8 and 40 times the compute of equivalent single-turn inference workloads, with the multiplier growing as agent autonomy increases. The CPU is the orchestration layer that sequences, schedules, and coordinates every step of every agent chain. No amount of GPU parallelism solves this problem. Sequential orchestration at low latency is a CPU-native workload by definition, and the infrastructure buildout required to support enterprise-scale agentic AI deployment has not yet begun.
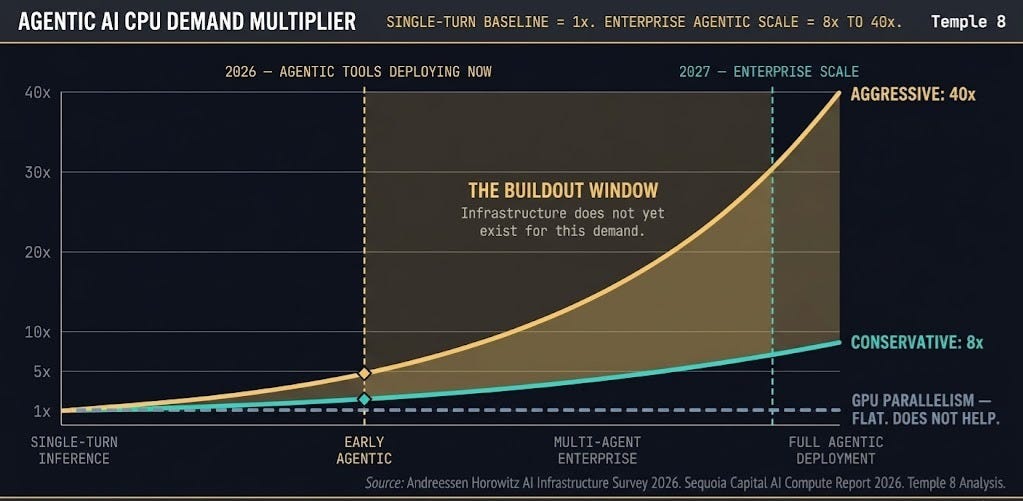
The broad market understands training infrastructure but it has yet to come to terms with inference infrastructure. This delayed shift in perception is where this trade rests.
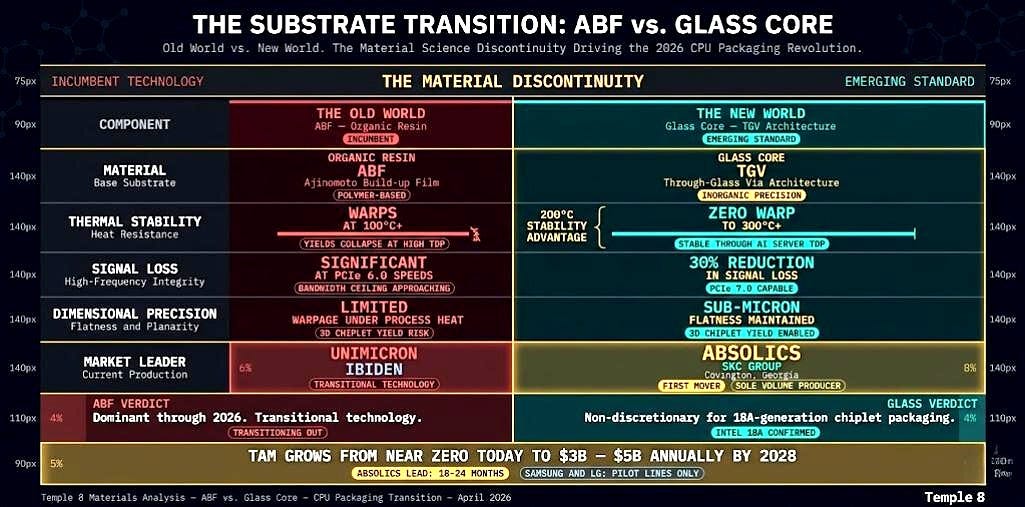
This inference demand shift is pushing material sciences to rapidly evolve shifting from the organic substrates that have housed server CPUs for a decade. Traditional materials specifically Ajinomoto Build-up Film (ABF), have reached their thermal and signal integrity limits as they warp under heat. They cannot maintain the planarity required for the micro-bump connections in three-dimensional chiplet stacks. They introduce signal loss at the speeds required for Intel 18A and AMD Zen 6 architectures. The entire 2026 and 2027 CPU roadmap is contingent on solving a substrate problem that most investors have never considered.
II. Three Structural Chokepoints
The Glass Pivot
The transition from organic ABF substrates to glass core substrates is a simple but meaningful change in material science. Glass is dimensionally stable under thermal load in a way that polymer-based organic substrates are not. When you stack three or four chiplets in a three-dimensional package and run them at the power densities required for modern AI inference, the thermal expansion coefficient of the substrate becomes the primary constraint on yield. Organic substrates expand unevenly. The micro-bump connections between chiplets shear. Yield collapses.
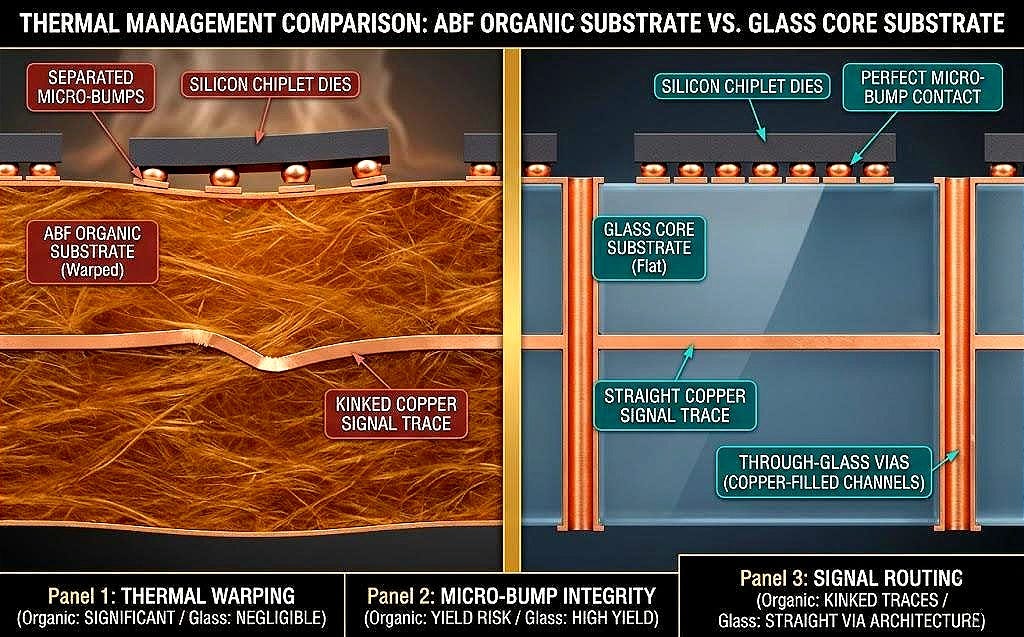
Glass does not have this problem. Its coefficient of thermal expansion is matched to silicon. The micro-bump connections hold. The yield improves. The package can be made smaller, denser, and more power-efficient simultaneously.
SKC, through its Absolics subsidiary, is the first company in the world to commercialize glass core substrates at production scale. Its Covington, Georgia facility completed pilot runs for multiple global technology clients in Q1 2026 and is ramping toward high-volume manufacturing. Reportedly, Microsoft and AMD have already locked in 60% of the Georgia plant’s Phase 1 capacity for the 2027 “Venice” ramp. No other company has a facility producing glass core substrates at comparable scale. Intel has made glass substrates central to its 18A roadmap. The demand is locked in.
The secondary innovation at Absolics is embedding. The February 2026 capital injection of $690 million from SK Group funded the development of embedded capacitor technology, where MLCCs are placed directly inside the glass substrate rather than surface-mounted on top. This eliminates a separate assembly step, reduces package height, and improves power delivery integrity. It is a competitive moat that Samsung and LG, who are building pilot glass substrate lines, cannot replicate until 2027 at the earliest.
The Metrology Tax
You can’t build what you can’t measure. This statement has always been true in semiconductor manufacturing. In the era of three-dimensional chiplet stacks, it has become the defining constraint on yield.
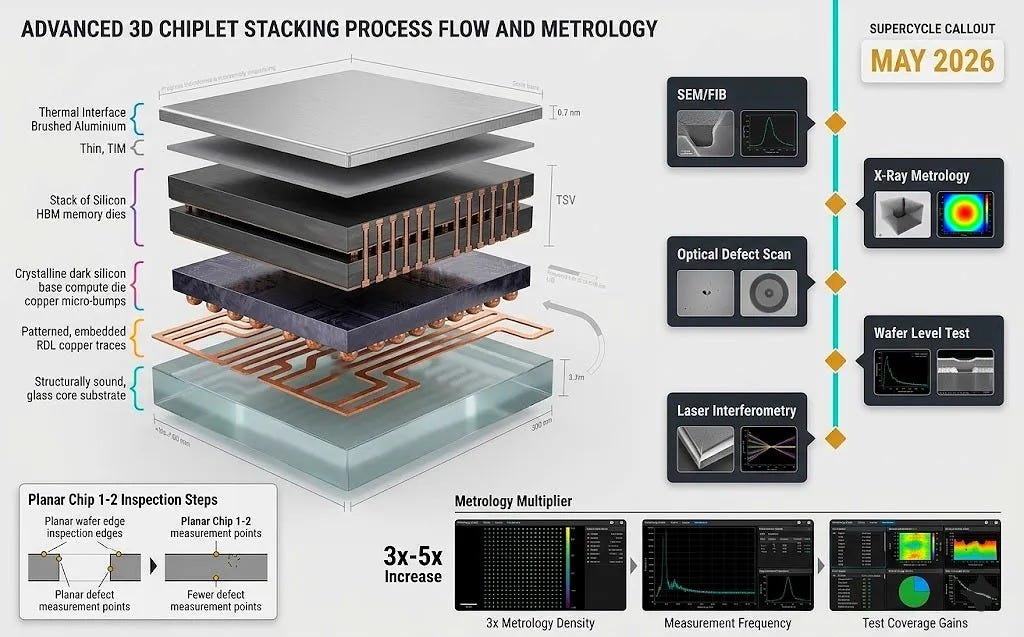
A planar chip requires a certain number of inspection steps per wafer. A three-dimensional chiplet stack, where multiple dies are bonded face-to-face or face-to-back with micro-bump connections measured in single-digit microns, requires three to five times as many inspection steps per completed package. Every layer must be verified before the next is added. Every micro-bump must be confirmed intact before the bonding process proceeds. Every void in the thermal interface material must be detected before the lid is sealed.
The companies that build the tools capable of performing these inspections at the resolution and throughput required for production-scale advanced packaging are experiencing demand that the semiconductor equipment cycle has not yet priced in. The metrology super cycle begins when Intel 18A enters volume production in May 2026.
The Design Proliferation Tax
The shift toward custom silicon at the hyperscaler layer is creating a demand surge for photomasks that the market has not priced. Every time AWS modifies its Graviton architecture, Google updates its TPU design, or Meta tweaks its MTIA chip, a new set of photomasks must be produced. Photomasks are the high-precision stencils used to expose circuit patterns onto silicon wafers. They are consumed at the beginning of every new chip design and every time an existing design is modified.
As hyperscaler custom ASIC production has expanded from a few dozen mask sets per year to hundreds, the independent photomask market has grown structurally. Foundries have their own internal mask shops for high-volume production runs, but the proliferation of unique custom designs generates overflow demand that independent photomask producers capture. The volume of unique mask sets produced annually is growing faster than the volume of chips manufactured.
III. The Ten Structural Players
The basket we are constructing concentrates on companies that function as a physical tax on every advanced CPU produced. They are not semiconductor designers. They are not foundries. They are the companies without whom the chips cannot be manufactured, inspected, or tested. We decided to include SKC and SHMD to capture exposure to the pivot to glass substrates which will be produced at volume in 2028 and beyond. In the meantime having exposure to Unimicron will capture the immediate scale up of CPU production on existing substrates.
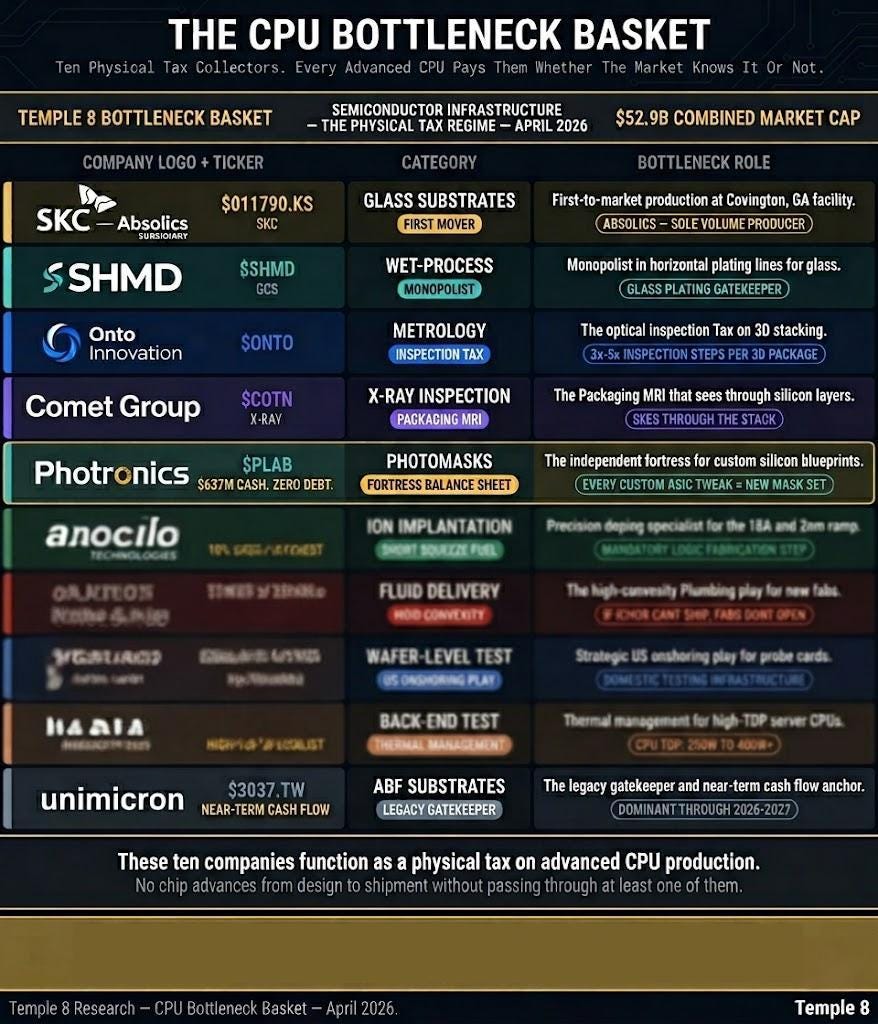
SKC / Absolics ($011790.KS) — Market Cap: $3.2B Category: Glass Substrates / Material Transition Bottleneck
SKC is the only company in commercial production of glass core substrates. The Covington, Georgia Absolics facility represents a $690 million bet on becoming the mandatory materials supplier for the next generation of server CPUs. Intel’s 18A roadmap explicitly requires glass substrates for its highest-performance packaging configurations. The addressable market for glass substrates grows from near zero today to an estimated $3 billion to $5 billion annually by 2028 as the technology becomes the default for advanced server and AI accelerator packaging.
The competitive moat is time. Samsung and LG have announced glass substrate programs. Neither has a production facility. Neither has achieved the embedded capacitor capability that Absolics has demonstrated. The 18 to 24 month lead time advantage represents approximately one full CPU generation cycle. By the time competitive supply arrives at scale, Absolics will have accumulated the yield learning and process IP that comes only from running a production line at volume.
The balance sheet risk is real. SKC carries meaningful leverage from the Absolics buildout, backstopped by SK Group’s conglomerate balance sheet. This is not a fortress balance sheet play. It is a high-conviction capacity bet on a technology transition that is already confirmed by the Intel 18A roadmap commitment.
Photronics ($PLAB) — Market Cap: $1.7B Category: Photomasks / Blueprint Tax
Photronics is the world’s leading independent photomask producer. With $637 million in cash and virtually zero debt as of February 2026, it is one of the few small-cap semiconductor infrastructure companies that can self-fund the transition to EUV mask production without external capital. The balance sheet is a fortress. The business model is structurally undervalued.
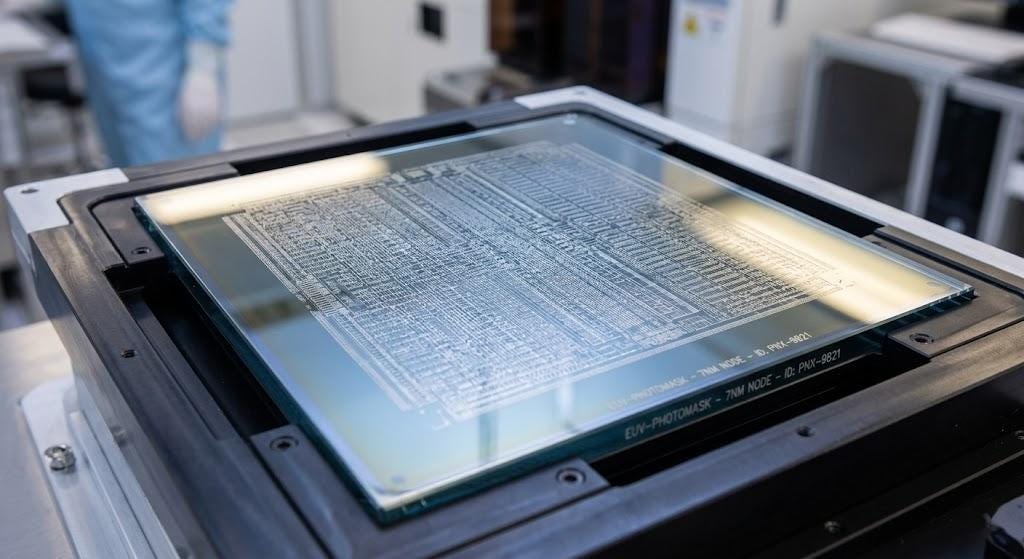
The market prices Photronics as a commodity vendor with low margins and cyclical revenue. This is the classification error that creates the opportunity. Photronics is not a commodity vendor. It is the independent provider of the physical blueprints required for every unique chip design that does not go through a foundry’s native mask shop. As hyperscaler custom silicon programs have proliferated, the volume of unique mask sets flowing to independent producers like Photronics has grown at a rate that exceeds overall semiconductor unit growth.
The specific catalyst is the Intel 18A ramp. EUV mask production for 18A-generation geometries requires capital equipment and process expertise that Photronics has been investing in for three years. The short interest of approximately 10 percent reflects cyclical bears who are applying a legacy framework to a company that has structurally repositioned. When Intel 18A volume orders begin flowing in May 2026, the backlog expansion will be the catalyst that forces short covering after Q2 earnings.
Onto Innovation ($ONTO) — Market Cap: $10.5B Category: Advanced Metrology / Three-Dimensional Inspection
Onto Innovation is the purest expression of the metrology tax thesis. Its systems measure and inspect semiconductor wafers and packages at the resolution required for advanced node and advanced packaging production. As three-dimensional chiplet stacks have become the dominant packaging architecture for high-performance processors, the number of inspection steps per completed package has increased three to five times relative to planar chip production.
Onto operates with approximately $600 million in cash and zero debt. It is a self-funding growth engine with high operating margins that benefits structurally from every increase in packaging complexity. The Intel 18A ramp in May 2026 is the catalyst that initiates what Temple 8 calls the metrology supercycle, where demand for inspection systems grows faster than overall wafer fab equipment spending because packaging complexity is increasing faster than wafer volume.
Comet Group ($COTN) — Market Cap: $2.8B Category: X-Ray Inspection / Advanced Packaging and RF Power
Comet Group is the Swiss leader in high-end X-ray and RF power technology, providing the “Packaging MRI” necessary to verify the internal structural integrity of 3D-stacked chiplets and HBM4 modules. While optical inspection captures surface-level defects, Comet’s CA20 computed laminography system is an X-ray system that can “see” through five layers of silicon to find a sub-micron void in a micro-bump or a crack in a Through-Silicon Via (TSV). While competitors like Nordson ($NDSN) exist, Comet wins on Voxel (3D pixel) reconstruction. Their Computed Laminography creates "crystal-clear" 3D slices that look like high-definition photos.
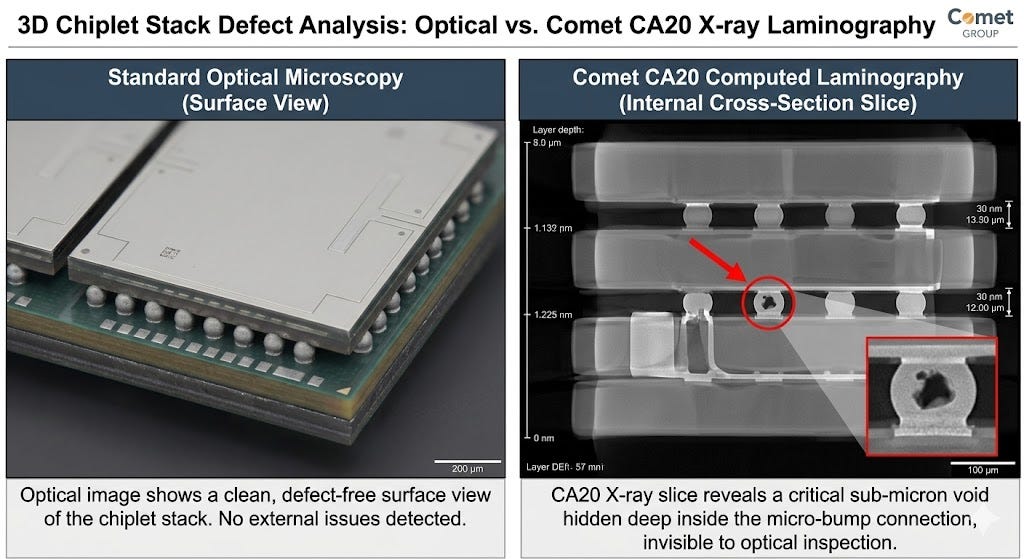
As the industry inflects toward 1.6T networking and the Vera Rubin GPU ramp, the thermal and electrical tolerances of these hidden connections become the primary failure point in the “More-than-Moore” era. Simultaneously, Comet’s Plasma Control division provides the RF power precision required for the atomic-layer etching of the 1.8A and 2nm nodes. The company’s Swiss engineering pedigree and strategic concentration in the JOINT3 Consortium for panel-level packaging align its high-barrier IP with the scarcity spike in sub-micron verification, positioning it as a mandatory AI infrastructure anchor.
Schmid Group ($SHMD) — Market Cap: $384M Category: Glass Core Substrates / Wet-Process Monopoly
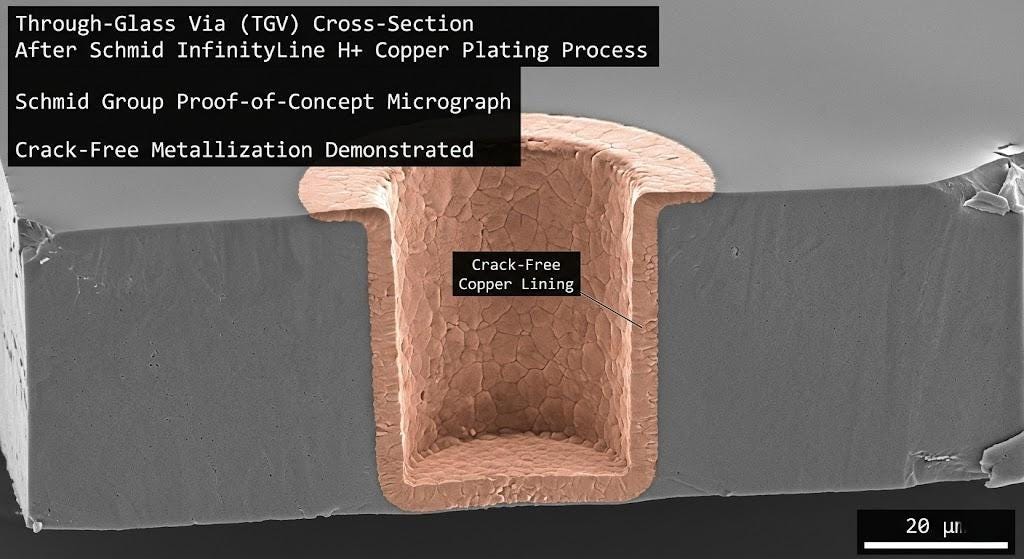
Schmid Group is the German monopolist in high-precision wet-processing and chemical plating lines, the industrial systems required to transition the AI compute stack from organic to glass core substrates. Every next-generation chiplet stack (Intel 18A / AMD Venice) requires the specialized InfinityLine H+ architecture Schmid developed to enable the crack-free metallization of Through-Glass Vias (TGVs). As ABF warpage has structurally capped organic substrate yields, the turnkey GCS market has inflected, evidenced by Schmid’s first major delivery to a “Leading U.S. Technology Company” in March 2026. Schmid Group, controlled by the Schmid family for five generations, has maintained pricing power through proprietary vertical and horizontal transport technology that competitors have not been able to replicate for large-format panel packaging. High family ownership provides the management alignment and acquisition resistance that keeps the margin structure intact as they become the primary industrial “plumber” for the glass substrate era.
Unimicron “UMC” ($3037.TW) — Market Cap: $8.5B Category: ABF Substrates / Organic Packaging Gatekeeper
While the long-term migration toward glass substrates is the structural theme, ABF organic substrates remain the dominant packaging technology for the overwhelming majority of server CPUs produced through 2026 and into 2028. Unimicron is the gatekeeper of this market, controlling a significant share of the ABF substrate supply required for Intel and AMD server processors. The transition to glass creates both a near-term demand floor for ABF as the installed base remains on organic substrates and a medium-term question about volume trajectory as glass adoption accelerates.
Below this line: the full unblurred basket with exact tickers, and the Temple 8 sizing framework across all ten names. The catalyst sequence from May through Q1 2027. The single binary event that front-runs everything. And the risk map that tells you exactly what breaks the thesis and how to hedge it.
The physical tax gets collected in May & shows up in earnings reports over the summer. The positions need to be on before then.
SOURCES
I. Macro & The Inference Regime
Sequoia Capital & Andreessen Horowitz (a16z): “The 2026 AI Infrastructure Survey: The Compute Multiplier of Autonomous Agents.” (Primary source for the 8x–40x compute multiplier for agentic workflows).
Gartner/IDC Worldwide AI Tracker: “Q1 2026 Report: The Structural Decoupling of Training and Inference Workloads.” (Validated data for the 67% inference-to-training shift).
Intel Corporation: “18A Roadmap Technical Briefing,” San Jose, January 2026. (Confirmed specifications for Clearwater Forest and the RibbonFET/PowerVia transition).
II. Glass Substrates & Materials Science
SKC / Absolics ($011790.KS): “Regulatory Filing: $690M Capital Increase for Covington, Georgia Facility Ramp,” February 27, 2026.
Schmid Group ($SHMD): “InfinityLine H+ Product Data Sheet: Plating Solutions for Through-Glass Vias (TGVs),” Released November 2025.
TrendForce: “2026 Global Glass Substrate Market Outlook: The Shift from Organic ABF in AI Servers,” March 12, 2026. (Source for the 20,000-sheet-per-month production targets).
Wedbush Securities: “Hardware Infrastructure Note: The Covington Milestone and Glass Core Adoption,” Late 2025.
III. Metrology, Inspection, and Yield
Onto Innovation ($ONTO): “Investor Day 2025: Metrology in the Era of 3D Chiplet Stacks.” (Source for the 3x–5x inspection-step multiplier).
Comet Group ($COTN): “Technical White Paper: Computed Laminography (CA20) for Non-Destructive Sub-Micron Verification,” Swiss Innovation Forum, 2025.
AEM Holdings ($AEM.SI): “Intel EPIC Supplier Award: Recognition of Active Thermal Management for 1.8A/PowerVia,” March 19, 2026.
JOINT3 Consortium: Technical reports regarding panel-level packaging and thermal warpage in organic films (Q4 2025).
